How Many Times Can You Refinance a Car Loan Today
You can refinance a car loan as many times as you want, but there are practical limits. Lenders look at your credit score, equity, and income each time. Multiple refinances can save money or hurt your finances if done poorly. This guide explains the rules, risks, and smart strategies for refinancing your car again and again.
Have you ever wondered how many times can you refinance a car? It is a question many car owners ask when they see interest rates drop or their credit score improves. The answer might surprise you. There is no legal limit on how many times you can refinance a car loan. You can do it two, three, or even more times. But just because you can does not mean you should. Each refinance comes with costs, risks, and benefits. This guide breaks it all down in simple terms. You will learn the rules, the limits, and the smart moves to make.
Car refinancing means replacing your current auto loan with a new one. The new lender pays off the old loan. You then make monthly payments to the new lender. People refinance to get a lower interest rate. They also refinance to lower their monthly payment. Sometimes they want to switch from a long loan term to a shorter one. Whatever your reason, understanding the process is key. How many times can you refinance a car depends on your financial picture each time you apply.
In this article, we will walk through every step. We will cover what happens when you refinance more than once. We will look at credit score requirements, equity rules, and fees. We will also share real examples and quick tips. By the end, you will know exactly when a second or third refinance makes sense. Let us dive in.
Key Takeaways
- No legal limit exists: You can refinance a car loan as many times as lenders approve you.
- Credit score matters every time: Each new refinance requires a hard credit pull and minimum score.
- Equity is king: You need positive equity or a low loan-to-value ratio to qualify again.
- Multiple refinances can save big: Lower rates and shorter terms reduce total interest paid.
- Watch for fees and penalties: Prepayment penalties and origination fees can erase your savings.
- Timing is critical: Waiting too long or refinancing too often can hurt your budget.
- Shop around each time: Rate shopping among multiple lenders ensures you always get the best deal.
📑 Table of Contents
- What Is Car Loan Refinancing and How Does It Work?
- How Many Times Can You Refinance a Car Loan?
- What Determines If You Can Refinance Again?
- The Pros and Cons of Refinancing Your Car Multiple Times
- Step-by-Step: How to Refinance Your Car Loan Again
- Final Thoughts: Is Multiple Refinancing Right for You?
What Is Car Loan Refinancing and How Does It Work?
The Basics of Refinancing a Car
Refinancing a car loan is like swapping an old loan for a new one. You keep the same car. The new lender pays off the remaining balance on your old loan. Then you start making payments to the new lender. The new loan may have a different interest rate. It may have a different term length. Sometimes the monthly payment goes down. Sometimes the loan term gets shorter. The goal is almost always to save money.
The process is simple. You apply with a lender. The lender checks your credit. They look at your income and the value of your car. If approved, you sign new loan documents. The old loan is closed. The new loan begins. This whole car refinancing process can take a few days to a few weeks.
When Should You Consider Refinancing?
Timing matters a lot. You should consider refinancing when your credit score has gone up. Interest rates may have dropped since you took the original loan. Maybe your monthly budget is tight and you need a lower payment. Or perhaps you want to pay off the car faster. These are all good reasons to explore an auto loan refinance. But do not refinance just for the sake of it. Each application can temporarily lower your credit score. You need a clear goal.
Quick Tips:
- Check your credit score for free before applying.
- Compare offers from at least three lenders.
- Know your car’s current market value.
- Calculate total costs, including any fees.
- Avoid refinancing if you are close to paying off the loan.
How Many Times Can You Refinance a Car Loan?
The Simple Answer: No Legal Limit
The short answer is there is no set number. You can refinance a car loan as many times as lenders will approve you. Federal and state laws do not cap the number of refinances. Each lender sets its own rules. Some lenders may not want to refinance a car that has been refinanced multiple times. But many will consider you again if you qualify. So how many times can you refinance a car really comes down to your financial health and the lender’s policies.
Think of it like this. Every time you refinance, you get a fresh loan. The lender looks at your current situation. They do not care how many times you refinanced in the past. They care about your credit now. They care about your income now. They care about the car’s value now. If you meet their criteria, you can refinance again.
How Many Times Is Too Many?
While there is no hard limit, too many refinances can cause problems. Each refinance adds a hard inquiry to your credit report. Too many inquiries can lower your score. Also, each new loan resets the clock on interest. If you refinance every six months, you might never build equity. You could end up paying more in fees than you save in interest.
A good rule of thumb is to wait at least six to twelve months between refinances. This gives your credit time to recover from the hard inquiry. It also ensures you are not just chasing tiny rate drops that do not save much money.
Common Mistakes:
- Refinancing too often just to get a slightly lower rate.
- Ignoring prepayment penalties on the old loan.
- Not calculating the total cost of the new loan versus the savings.
- Rolling negative equity into the new loan.
- Choosing a longer term just to lower the payment, which increases total interest.
What Determines If You Can Refinance Again?
Your Credit Score and Credit History
Your credit score is the biggest factor. When you apply for a car loan refinance, the lender pulls your credit. They want to see a strong payment history. Late payments or defaults make approval harder. A score of 661 or higher is usually needed for good rates. If you have been improving your credit since the first refinance, you may qualify for an even better rate the second time around.
Lenders also look at your credit utilization. This is how much of your available credit you are using. Keeping it below 30% helps your application. A long history of on-time payments is a huge plus. Even if you have refinanced before, a clean recent history can win over a lender.
Equity and Loan-to-Value Ratio
Equity means the part of the car you truly own. If your car is worth $20,000 and you owe $15,000, you have $5,000 in equity. Lenders want to see positive equity or a low loan-to-value ratio. This reduces their risk. If you have negative equity, meaning you owe more than the car is worth, getting approved again is tough. Some lenders will refinance negative equity, but they may charge a higher rate or require you to roll the negative balance into the new loan.
Expert Insights: According to industry experts, lenders typically require a loan-to-value ratio below 125%. This means your new loan amount should not exceed 125% of the car’s appraised value. Staying well below that number gives you more options.
Income and Debt-to-Income Ratio
Lenders also check your income. They want to know you can handle the new monthly payment. Your debt-to-income ratio is the percentage of your monthly income that goes to debt payments. A lower ratio is better. If you have refinanced before, your new payment will be part of this ratio. Keeping your income stable and your other debts low makes each new refinance easier.
Quick Tips:
- Pay down other debts before applying for another refinance.
- Avoid major credit purchases right before refinancing.
- Keep your employment steady if possible.
- Gather proof of income, such as pay stubs or tax returns.
The Pros and Cons of Refinancing Your Car Multiple Times
Why You Might Refinance More Than Once
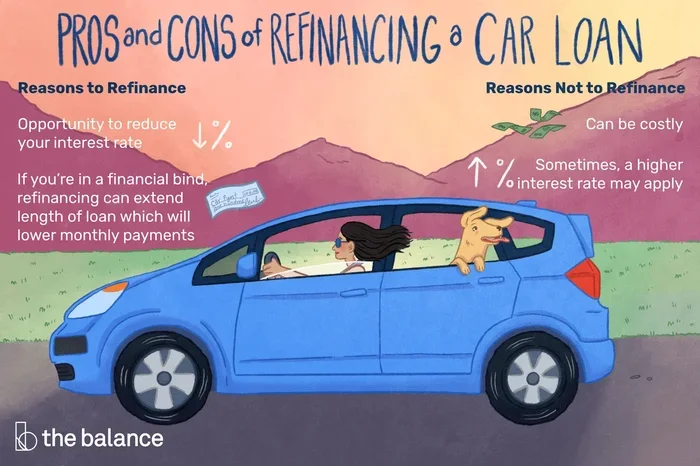
There are real benefits to refinancing your car again. The biggest one is saving money. A lower interest rate means less interest over the life of the loan. For example, if you refinanced from 8% to 5%, you could save hundreds or even thousands of dollars. You might also lower your monthly payment. This frees up cash in your monthly budget for other bills or savings.
Another benefit is adjusting the loan term. If your financial situation changes, you can switch from a 72-month loan to a 48-month loan. This helps you pay off the car faster. You can also switch from a short term to a longer term if you need a lower payment. Each refinance car decision is a chance to better match your current needs.
The Hidden Risks of Too Many Refinances
But there are risks. Every time you refinance, you may pay an origination fee. Some lenders charge $200 to $500. There may also be prepayment penalties on the old loan. If you have to pay a penalty, it eats into your savings. Also, each hard inquiry can drop your credit score by a few points. Over time, this adds up.
Another risk is extending the loan term too much. If you refinance a 3-year loan into a 5-year loan, your monthly payment drops. But you end up paying more in total interest. The car also loses value over time. If you refinance too many times, you might end up underwater again, owing more than the car is worth.
Comparison Table:
| Refinancing Once | Refinancing Multiple Times |
|---|---|
| One-time application fee | Cumulative fees from each refinance |
| One hard credit inquiry | Multiple hard inquiries, score impact |
| Single payoff balance | Rolling costs or negative equity risk |
| Clear savings if rate drops | Savings may shrink if done too often |
| Simpler process | More paperwork and lender comparisons |
| One new loan term | Potential for longer terms and more interest |
Key Takeaways:
- Refinancing once can save a lot of money with minimal risk.
- Multiple refinances require careful math to ensure net savings.
- Always compare the total cost of the new loan to the old one.
- Keep an eye on your credit score after each application.
Step-by-Step: How to Refinance Your Car Loan Again
Step 1 – Check Your Credit and Gather Documents
Before you start, pull your credit report. Fix any errors you find. Gather your most recent pay stubs, tax returns, and bank statements. You will also need your current loan details. Know the payoff balance, the monthly payment, and the remaining term. This preparation makes the refinancing process smoother and faster.
Step 2 – Get Preapproved and Compare Offers
Next, apply for preapproval with several lenders. Many banks, credit unions, and online lenders offer preapproval with a soft credit check. This does not hurt your score. Compare the interest rates, terms, and fees they offer. Look at the annual percentage rate, or APR. The APR includes both the interest rate and any fees. This gives you a true cost comparison. Do not just look at the monthly payment. Look at the total amount you will pay over the life of the loan.
Expert Insights: Rate shopping within a 14-day window counts as a single hard inquiry on most credit scoring models. So you can apply to several lenders in a short time without harming your score further.
Step 3 – Pay Off the Old Loan and Close the Deal
Once you choose the best offer, the new lender will pay off your old loan. They usually send the funds directly to the old lender. You then start making payments to the new lender. Make sure the old loan is fully closed. Check your credit report to confirm the old account shows a zero balance. Keep all documents for your records.
Quick Tips:
- Set up autopay on the new loan to avoid missed payments.
- Make a final payment on the old loan if there is a small remaining balance.
- Verify the new loan details match the offer you accepted.
- Cancel any automatic payments set up for the old loan.
Final Thoughts: Is Multiple Refinancing Right for You?
Weighing the Savings Against the Costs
So, how many times can you refinance a car? The answer is as many times as you can get approved for and as many times as it makes financial sense. There is no magic number. Each situation is different. If you are deep into a car loan and rates have dropped significantly, a second or even third refinance can be a smart move. But you must do the math. Calculate the total fees against the total savings. If the savings are greater, it is worth it. If not, it is better to wait.
Think about your long-term goals. Do you want to be car payment free sooner? Then a shorter loan term might be better. Do you need more breathing room in your monthly budget? Then a lower payment might be the priority. Whatever you choose, make sure each refinance brings you closer to your financial goals.
Remember, how many times can you refinance a car is not just about the number. It is about the quality of each refinance. Do it when the numbers make sense. Do it when your credit is strong. Do it when you have a clear plan. Avoid refinancing just because it feels good to get a new loan. Every loan has a cost. Make sure the cost is worth the benefit.
Take action today. Check your credit. Review your current loan. Compare offers from multiple lenders. You might be surprised at how much you can save. A smart car loan refinance can put hundreds of dollars back in your pocket every year. Do not let hesitation keep you from exploring your options. The more you know, the better your decisions will be.
Frequently Asked Questions
Can I refinance my car loan if I still owe more than it is worth?
Yes, but it is harder. Some lenders offer negative equity refinancing. They may roll the negative balance into the new loan. This increases your loan amount and may come with a higher interest rate. It is best to wait until you have positive equity if possible.
Does refinancing a car hurt your credit score?
A single refinance causes a small, temporary dip due to a hard credit inquiry. The drop is usually a few points and recovers within a few months. Multiple refinances close together can have a bigger impact. Space out your applications to minimize the effect.
How long should I wait between car refinances?
Wait at least six to twelve months between refinances. This lets your credit recover from hard inquiries. It also ensures you are not just chasing minor rate drops that do not save meaningful money. Each refinance should offer clear savings.
Are there fees for refinancing a car loan?
Yes, many lenders charge origination fees. Some old loans have prepayment penalties. Always read the fine print before signing. Calculate the total fees and subtract them from your projected savings to see if refinancing is still worth it.
Can I refinance a car that I bought from a private seller?
Yes, you can refinance a car bought from a private seller. The process is the same. The lender will appraise the vehicle. They will check your credit and income. As long as you meet their requirements, you can refinance regardless of who sold you the car.
Will a second refinance get me the same low rate as the first?
Not necessarily. Rates depend on current market conditions and your credit profile at the time of the second application. If your credit has improved and rates have dropped further, you may get an even lower rate. If your credit has slipped, the rate may be higher than your first refinance.