Can You Drive a Totaled Car and Still Get Back on the Road
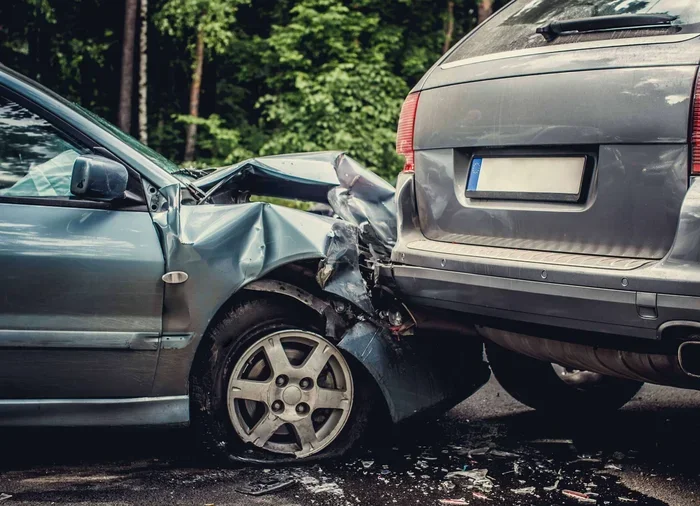
Yes, you can drive a totaled car under certain conditions, but it depends on your state laws, the extent of damage, and whether your vehicle has a salvage or rebuilt title. A totaled vehicle means your insurance company has decided the repair costs exceed the car’s actual value. Before you get behind the wheel again, you need to understand the legal requirements, safety risks, and insurance implications involved in owning a totaled car.
Getting told your car is totaled hits hard. You look at the vehicle and think, “It still runs. Why can’t I just keep driving it?” The truth is, the answer to can you drive a totaled car is not a simple yes or no. It depends on a mix of state laws, insurance rules, safety factors, and the type of damage your vehicle sustained. Many people assume a totaled car means the end of the road, but that is not always the case.
In this guide, we will walk you through everything you need to know about driving a totaled vehicle. We will cover what “totaled” actually means, how insurance companies decide a total loss, whether you can legally drive the car, and what steps to take next. Whether you are dealing with a flood-damaged car, a frame-damaged vehicle, or just a car with expensive repairs, this article has you covered.
By the end, you will have a clear picture of your options. You will know what a salvage title is, how to get a rebuilt title, what to watch out for with hidden damage, and how to make a smart decision about your totaled vehicle. Let us get into it.
Key Takeaways
- You may legally drive a totaled car: In many states, you can drive a totaled vehicle after obtaining a salvage or rebuilt title and passing a safety inspection.
- Insurance is still required: You must maintain at least minimum liability coverage even if your car has a salvage or rebuilt title.
- Safety comes first: Structural damage, airbag deployment, and frame issues can make a totaled car unsafe to drive regardless of legal status.
- Insurance payouts vary: You can choose between a cash settlement, keeping the car with a reduced payout, or repairing it yourself.
- Getting a rebuilt title is a process: It requires documentation, inspections, and fees, but it makes your vehicle roadworthy again in the eyes of the law.
- Not every totaled car is worth repairing: Compare repair costs against the vehicle’s pre-loss value before making a decision.
- Know your state laws: Regulations around totaled vehicles differ significantly from state to state.
📑 Table of Contents
- What Does It Mean When a Car Is Totaled?
- Can You Drive a Totaled Car Legally?
- How Insurance Companies Handle Totaled Vehicles
- Safety Concerns of Driving a Totaled Car
- Steps to Take After Your Car Is Totaled
- When Does It Make Sense to Repair a Totaled Car?
- Legal Requirements and Roadworthiness
- Frequently Asked Questions
- Conclusion
What Does It Mean When a Car Is Totaled?
When an insurance company says your car is totaled, it means they have classified it as a total loss. This does not mean the car is destroyed beyond recognition. It means the cost to repair the vehicle exceeds a certain percentage of its pre-loss value. Every state has its own threshold, but most insurance companies total a car when repair costs reach 70 to 90 percent of the vehicle’s actual cash value.
How Insurance Companies Decide a Total Loss
Your insurance adjuster evaluates the damage and estimates repair costs. They also look at the car’s pre-accident value based on factors like age, mileage, condition, and market demand. If the estimated repairs plus the salvage value of the car exceed the vehicle’s actual cash value, the insurer declares it a total loss. At that point, you receive a payout based on the car’s pre-loss market value minus your deductible.
For example, imagine your car was worth $15,000 before an accident. The repair estimate comes back at $12,000. The salvage value might be $3,000. So the total cost to the insurer would be $12,000 in repairs minus $3,000 salvage, which equals $9,000. Since $9,000 is less than the car’s value of $15,000, they might still repair it. But if the repair estimate was $13,000, the total cost would be $10,000, and many insurers would still total the car because the numbers do not make financial sense for them.
Quick Tips
- Always get your own independent car damage assessment before accepting a total loss offer.
- Know your car’s market value using tools like Kelley Blue Book or Edmunds before the accident.
- Ask your adjuster for a detailed breakdown of the repair estimate.
The Total Loss Threshold by State
Each state sets its own rules for when a car qualifies as a total loss. Some states use a fixed percentage threshold, while others use a total loss formula. In a threshold state, if repairs exceed a set percentage of the car’s value, it is automatically totaled. In a formula state, the adjuster adds the repair costs to the salvage value and compares that to the car’s actual value.
States like Arizona, Colorado, and Maryland use a 75 percent threshold. Others like New York and Louisiana use a 70 percent threshold. A few states, like Texas, use a total loss formula instead of a fixed percentage. This means the rules can vary a lot depending on where you live. If you are wondering about the specific laws in your area, it is worth checking with your state’s department of motor vehicles or your insurance agent.
Can You Drive a Totaled Car Legally?
The short answer is maybe. Whether you can legally drive a totaled car depends on the status of the vehicle’s title and your state’s regulations. Once a car is declared a total loss, the insurance company typically takes ownership or issues a salvage title. From that point, the vehicle’s legal status changes, and there are specific rules you must follow.
Understanding Salvage Titles
A salvage title is issued when a vehicle has been declared a total loss. The car is considered unfit for the road in its current condition. With a salvage title, you generally cannot register the vehicle or drive it on public roads without making repairs and going through a specific process. The salvage title serves as a warning to future buyers that the vehicle has significant damage history.
However, there are some exceptions. In a few states, you may be allowed to drive a salvage-titled vehicle directly to a repair shop or inspection facility. This is usually a temporary permit and only applies for short distances. You should never assume you can drive freely on public roads with a salvage title without checking your local laws first.
The Rebuilt Title Process
A rebuilt title is what you get after you repair a salvage vehicle and pass a state inspection. The rebuilt title proves that the car has been restored to a roadworthy condition and meets all safety and emissions requirements. Once you have a rebuilt title, you can legally register and drive the vehicle just like any other car on the road.
The process for getting a rebuilt title varies by state but generally follows these steps:
- Repair all damage to the vehicle using quality parts and licensed mechanics.
- Gather all repair documentation, including invoices and parts receipts.
- Submit the paperwork to your state’s motor vehicle agency.
- Schedule and pass a safety inspection and sometimes an emissions test.
- Pay the required fees for the rebuilt title and registration.
This process can take anywhere from a few weeks to a few months depending on your state’s requirements and the extent of repairs needed. Make sure you keep every receipt and document every step. Inspectors will want to see proof that all systems have been properly restored.
Common Mistakes
- Skipping the inspection: Driving a car with a salvage title without a rebuilt title can result in fines, impoundment, and voided insurance coverage.
- Keeping a salvage title hidden: When you sell a rebuilt vehicle, you must disclose the salvage history. Hiding this information is illegal in most states.
- Using substandard parts: Some states will reject your rebuilt title application if non-OEM or low-quality parts were used in the repairs.
How Insurance Companies Handle Totaled Vehicles
Dealing with insurance after a car is totaled can feel overwhelming. Understanding how the process works helps you make informed decisions and avoid common pitfalls. Your insurance company has specific procedures for handling total loss claims, and knowing them puts you in a stronger position.
Insurance Payout Options
When your car is declared a total loss, your insurer offers you a payout based on the vehicle’s actual cash value at the time of the accident. This is not the amount you originally paid for the car. It is the market value at the moment of the loss, accounting for depreciation. You generally have a few options for how to handle the payout:
- Accept the settlement: Take the cash payout, sign over the title, and let the insurance company handle the vehicle. This is the most common route.
- Keep the car with a reduced payout: Some insurers let you keep the totaled vehicle but reduce your payout by the salvage value. You then take on the responsibility of repairs and title changes.
- Dispute the valuation: If you believe the insurance company’s offer is too low, you can provide evidence of the car’s value, such as recent maintenance records, upgrades, or comparable listings in your area.
Filing a Claim for a Totaled Car
The claims process typically starts with reporting the accident or damage to your insurance company. An adjuster will be assigned to evaluate the vehicle. They may require photos, a police report, and a detailed description of the damage. Once the adjuster completes their assessment, the insurance company will either offer a settlement or deny the claim.
If you have comprehensive coverage or collision coverage, your totaled vehicle claim will be covered up to the policy limits. If you only carry liability coverage, damage to your own vehicle will not be covered. This is why having the right insurance policy matters so much. A quick tip: always review your policy details before an accident happens so you know exactly what is covered.
Expert Insights
Insurance experts recommend shopping around for your car’s pre-loss value if you disagree with the initial offer. Use multiple sources like NADA Guides, local dealership listings, and online valuation tools to build a strong case. Having solid evidence can increase your payout by hundreds or even thousands of dollars.
Safety Concerns of Driving a Totaled Car
Even if a totaled car still runs, that does not mean it is safe to drive. Safety should always be your top priority when considering whether to operate a damaged vehicle. Some types of damage are obvious, while others are hidden and dangerous.
Structural Damage Risks
Structural damage is the most serious concern with a totaled vehicle. If the frame or unibody has been bent, cracked, or compromised, the car’s structural integrity is weakened. In a second collision, a vehicle with frame damage may not provide the same level of protection as a properly structured car. The crumple zones designed to absorb impact may not function correctly, putting you and your passengers at greater risk.
Frame damage often results from high-speed collisions, side impacts, or rollovers. Even if the car appears drivable on the surface, the underlying structural issues can make it dangerous. A vehicle history report from services like Carfax or AutoCheck can sometimes reveal past frame damage, but a professional inspection is always the best way to be sure.
Hidden Damage You Cannot See
Not all damage is visible from the outside. Some of the most dangerous problems with a totaled car are hidden beneath the surface:
- Airbag deployment: If airbags deployed during the accident, the supplemental restraint system may not work correctly if not properly replaced.
- Electrical system damage: Wiring harnesses can be compromised, leading to intermittent electrical failures or even fire risks.
- Fluid leaks: Damaged brake lines, fuel lines, or coolant hoses may not be immediately visible but pose serious safety hazards.
- Suspension and steering damage: Misaligned suspension components can affect handling and control, especially at higher speeds.
Before you consider driving any totaled vehicle, have a trusted mechanic perform a thorough inspection. They can identify hidden issues that you might miss on your own. This inspection could save your life.
Quick Tips
- Never drive a totaled car if the airbags did not deploy properly or were not replaced.
- Check for fluid leaks underneath the car before starting the engine.
- Test all lights, brakes, and steering before driving any damaged vehicle.
- If something feels off while driving, pull over immediately and have the car towed.
Steps to Take After Your Car Is Totaled
Finding out your car is totaled can be stressful, but knowing what to do next helps you stay organized and make the best decision. Here is a clear roadmap to follow:
- Contact your insurance company right away. Report the incident and start the claims process as soon as possible. Delays can complicate your claim.
- Document everything. Take photos of the damage, keep all repair estimates, and save all communication with your insurer. Documentation protects you if disputes arise later.
- Get your vehicle’s pre-loss value. Research what your car was worth before the accident using multiple valuation sources. This strengthens your position if you need to negotiate the payout.
- Decide whether to accept the total loss or keep the car. If you want to repair the vehicle, make sure the repair costs are reasonable compared to the car’s value. If the payout is fair, accepting it may be the smarter choice.
- Apply for a salvage or rebuilt title if you keep the car. Follow your state’s process for title transfer and inspection requirements.
- Update your insurance policy. If you keep the vehicle, you will need to maintain insurance coverage. A rebuilt title car can still be insured, but premiums may be higher.
Taking these steps in order keeps you organized and ensures you do not miss anything important. Many people rush through the process and later face problems with registration, insurance, or safety issues that could have been avoided.
When Does It Make Sense to Repair a Totaled Car?
Not every totaled car should be repaired, and not every totaled car needs to be scrapped. The decision comes down to a simple cost-benefit analysis. If the repair costs are significantly lower than the vehicle’s pre-loss value, and the car is safe to drive after repairs, fixing it can be a smart move.
Here are some situations where repairing a totaled car makes sense:
- The damage is primarily cosmetic or affects non-structural components like the bumper, hood, or doors.
- The repair costs are well below the total loss threshold for your state.
- The vehicle had no prior damage and was in good condition before the accident.
- You have a strong emotional attachment to the car and it holds sentimental value.
- You can afford the repairs out of pocket and do not need the insurance payout.
On the other hand, there are clear situations where you should not repair a totaled car:
- The vehicle has extensive frame damage or structural compromise.
- Repair costs exceed 75 to 90 percent of the car’s pre-loss value.
- The car had significant pre-existing damage before the accident.
- The diminished value after repairs would make the car worth much less on the resale market.
- Safety systems like airbags, brakes, or steering were compromised and the repair costs are prohibitive.
A useful rule of thumb is the 75 percent rule. If repairs cost more than 75 percent of the car’s pre-loss value, it is usually not worth fixing. The car will never be worth what it was before the accident, and you will carry the burden of a rebuilt title going forward.
Totaled Car Decision Guide
| Factor | Repair the Car | Accept the Total Loss |
|---|---|---|
| Repair Cost vs. Vehicle Value | Less than 70 percent | More than 75 percent |
| Structural Damage | None or minor | Extensive frame or unibody damage |
| Safety Systems | All functional or properly replaced | Airbags, brakes, or steering compromised |
| Title Status | Rebuilt title obtained | Salvage title surrendered to insurer |
| Insurance Coverage | Comprehensive or collision coverage | Policy limits cover full actual cash value |
| Long-Term Outlook | Car remains reliable after repairs | Diminished value and potential future issues |
Expert Insights
Automotive experts suggest getting at least three independent repair estimates before deciding to fix a totaled car. This gives you a realistic picture of the costs involved. Additionally, consider the diminished value of the car after repairs. Even a perfectly fixed totaled car typically sells for 20 to 40 percent less than a comparable vehicle with no accident history. This hidden cost is something many people overlook.
Legal Requirements and Roadworthiness
Every state has specific legal requirements for vehicles on public roads. A totaled car that has not been properly repaired and re-inspected does not meet these requirements. Driving an unregistered or improperly titled vehicle can result in fines, license suspension, and even impoundment of the vehicle.
Before you drive any car with a salvage or rebuilt history, make sure you have met all legal requirements in your state. This includes having the correct title, passing all required inspections, and maintaining valid insurance coverage. The roadworthiness of a vehicle is not just about whether the engine starts and the wheels turn. It is about ensuring every safety system functions as intended to protect you and others on the road.
Some states also require a VIN verification for rebuilt title vehicles. This involves a law enforcement officer or authorized inspector confirming the vehicle identification number matches the paperwork. It is a simple step that prevents fraud and ensures accountability in the vehicle restoration process.
Frequently Asked Questions
Can I drive a totaled car home from the accident scene?
In most cases, yes, you can drive the car home from the accident scene if it is still operational and safe to drive. However, this depends on your state laws and the severity of the damage. Some states require that a totaled vehicle be towed rather than driven. If the car has any visible structural damage, fluid leaks, or compromised safety systems, it should be towed to a repair facility instead of driven.
How long does it take to get a rebuilt title?
The timeline for getting a rebuilt title varies by state but typically ranges from two to eight weeks. The process involves completing all repairs, gathering documentation, scheduling a state inspection, and submitting paperwork to the DMV. States with more rigorous inspection processes may take longer. Keeping all your receipts and documentation organized will help speed up the process.
Will a rebuilt title lower my car’s value?
Yes, a rebuilt title almost always reduces a vehicle’s market value. Most buyers are hesitant to purchase a car with a salvage or rebuilt history, even if the repairs were done professionally. On average, a rebuilt title car is worth 20 to 40 percent less than a clean title vehicle in similar condition. This diminished value is an important factor to consider before deciding to repair a totaled car.
Can I get insurance for a car with a salvage title?
Getting insurance for a salvage title car is very difficult because most insurers will not cover a vehicle that is not roadworthy. However, once you have a rebuilt title and the car has passed inspection, you can typically get insurance coverage. Keep in mind that premiums for rebuilt title vehicles are often higher than for clean title cars, and some insurers may only offer liability coverage, not comprehensive or collision.
What happens if I drive a car with a salvage title without a rebuilt title?
Driving a vehicle with a salvage title on public roads without a rebuilt title is illegal in most states. Penalties can include fines, vehicle impoundment, points on your driver’s license, and potential suspension of your registration. In some cases, you may also void your insurance coverage, meaning you would be personally liable for any damages or injuries that occur.
Is a totaled car ever worth repairing?
A totaled car can be worth repairing if the damage is minor, the repair costs are well below the vehicle’s pre-loss value, and the car is safe to drive after repairs. Cosmetic damage, minor bumper or panel damage, and non-structural issues are often worth fixing. However, if the car has frame damage, compromised safety systems, or repair costs that exceed 75 percent of its value, it is usually better to accept the insurance settlement and move on.
Conclusion
The question of can you drive a totaled car does not have a one-size-fits-all answer. It depends on your state’s laws, the type and extent of damage, your insurance policy, and your personal goals for the vehicle. The key takeaway is that driving a totaled car is possible in many cases, but it requires following the proper legal steps, ensuring the vehicle is safe, and maintaining the right insurance coverage.
Whether you choose to repair your vehicle and obtain a rebuilt title, or accept the insurance settlement and move on, the most important thing is to make an informed decision. Weigh the costs, consider the safety implications, and understand the long-term impact on your vehicle’s value and insurability. A totaled car is not necessarily the end of the road, but it does require careful thought and responsible action to get back on it safely.
Take the time to understand your options, consult with professionals, and never compromise on safety. With the right approach, you can navigate the totaled car process with confidence and make the best choice for your situation.